Kenya’s payments overhaul puts remittances at the centre of FX debate
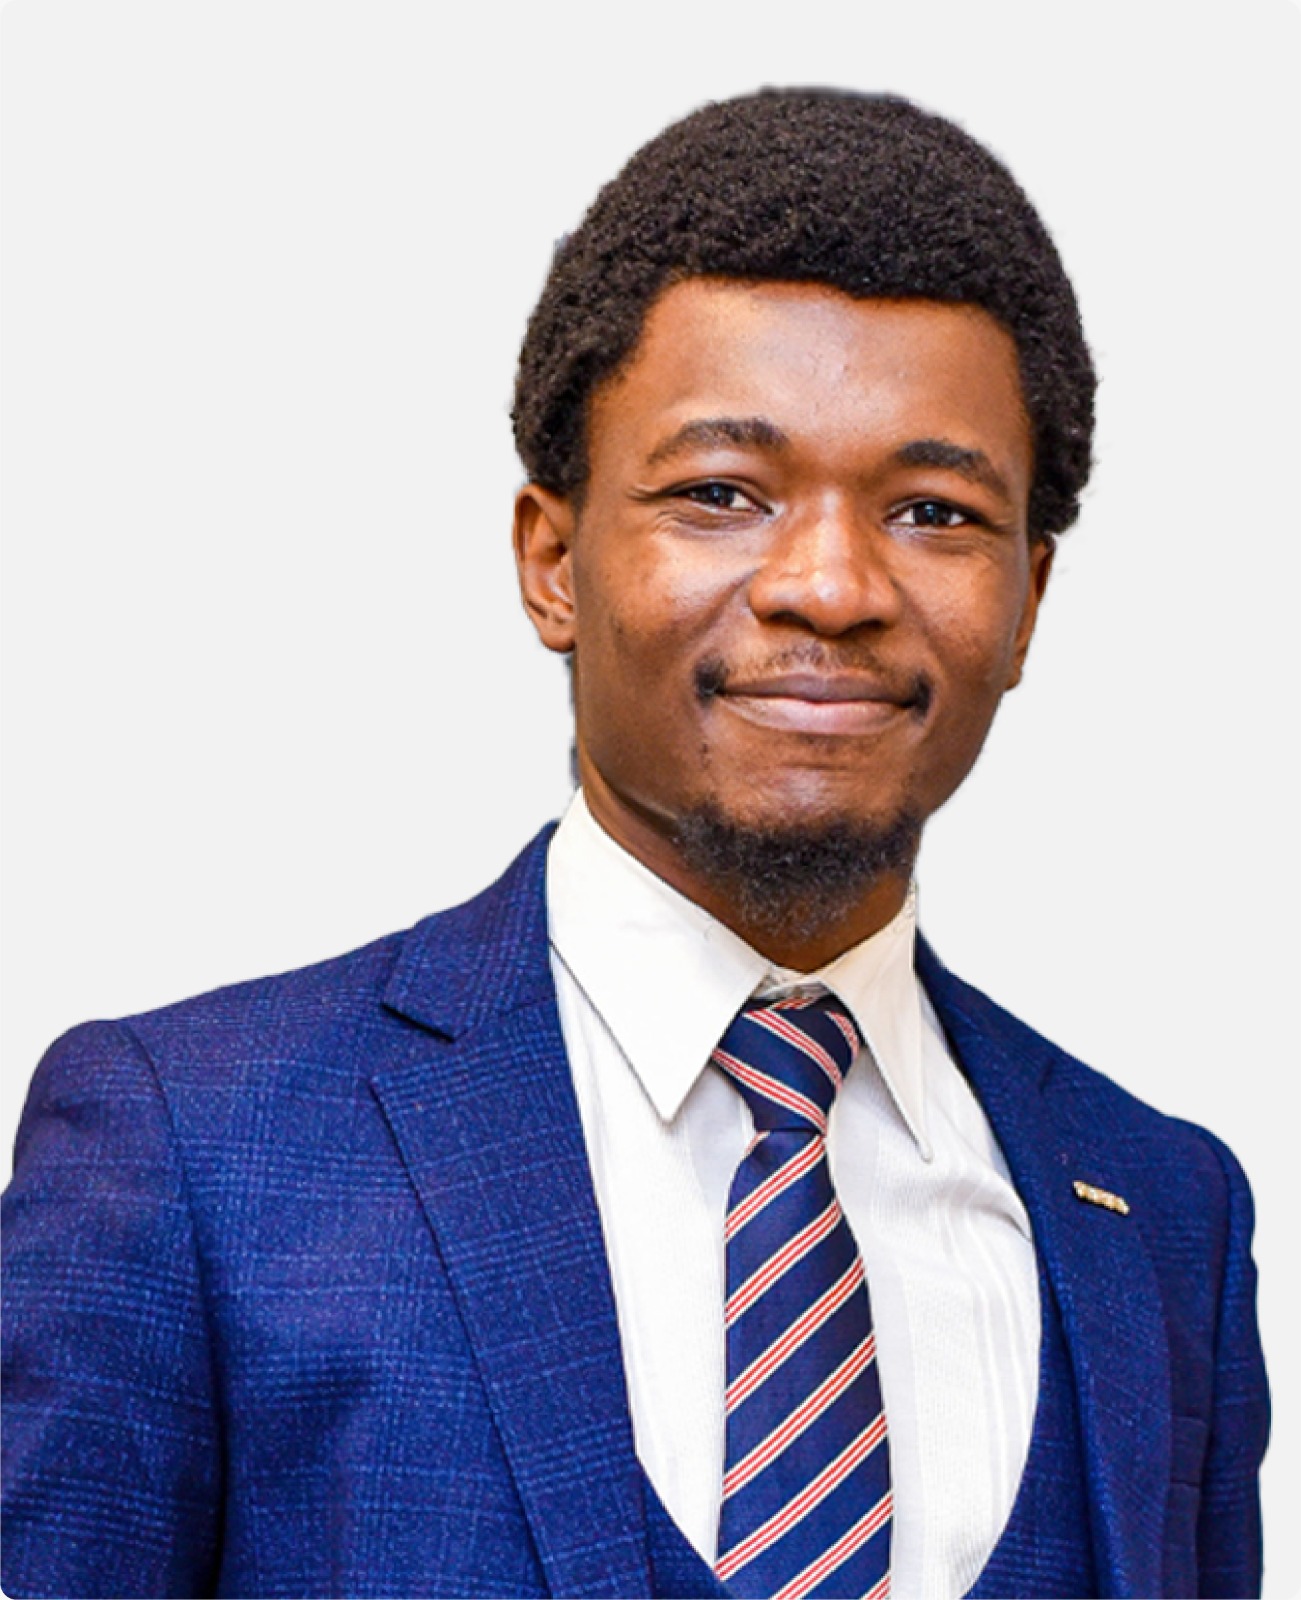
David Precious, Senior Market Analyst, EBC Financial Group
Diaspora transfers face rising costs as reforms test resilience of financial rails
By James Mwangi
Kenya’s proposed reform of its national payments system has ignited debate well beyond the fintech and competition circles. At the heart of the discussion lies the country’s USD5 billion remittance economy, a lifeline for millions of households and the single largest source of foreign exchange. As consultations on the draft National Payment System Policy and Bill, 2026 continue, the question is whether the new framework can deliver efficiency, resilience, and affordability at a time when annual remittance growth is no longer guaranteed.
The National Treasury and the Central Bank of Kenya (CBK) unveiled the draft policy and Bill on 21 September, setting out proposals that include raising capital requirements for remittance providers, introducing a national instant payment switch, and mandating interoperability between payment systems. Public comments remain open until 9 October, with 11 forums underway across the country. The reforms promise faster and more connected transfers, but they stop short of tackling the fees senders pay — costs shaped by provider charges, exchange‑rate margins, intermediary bank fees, and taxes imposed in sending countries. For families relying on diaspora support, the difference between a seamless transfer and an affordable one is critical.
CBK data illustrates the challenge. Kenya received a record USD451.8 million in August, up 6.0% from USD426.1 million a year earlier. Yet over the 12 months to August, inflows fell 1.3% to USD5.013 billion, below the USD5.04 billion received in 2025. If end‑year transfers do not recover, 2026 could mark the first annual decline since 2009. The United States, which accounts for nearly half of Kenya’s remittances, saw inflows drop 12.6% after a 1% tax on cash‑funded transfers took effect in January. New transaction taxes in Saudi Arabia have also weighed on Middle East flows. CBK Governor Kamau Thugge warned in April that these external factors could dampen growth, underscoring the limits of domestic reforms in shielding Kenya from global policy shifts.
David Precious, Senior Market Analyst at EBC Financial Group, observed that diaspora transfers amount to roughly two months of Kenya’s imports. “Higher costs may push some senders to informal channels that official data may not capture, leaving Kenya with less foreign currency,” he said. EBC argues that while the Bill’s proposals on speed and interoperability could reduce friction, they will not automatically lower fees. A 2025 household survey found that 83.3% of recipients cited high costs as their biggest challenge. World Bank data showed average fees of 4.26% for sending USD200 from the US to Kenya, above the UN’s 3% target for 2030. Cash‑to‑cash transfers reached as high as 11.26%, while card‑ or bank‑funded transfers to mobile wallets were under 2%. These figures predate the US tax, meaning costs may now be even higher.
The Bill introduces a new licence category for Money Remittance Service Providers and raises minimum capital requirements from KSh20 million to KSh30 million. Supporters say this could strengthen providers’ financial stability, protecting customers from sudden failures. Critics warn it may reduce competition by squeezing out smaller players, potentially driving up prices and limiting access. The instant payment switch and interoperability rules are designed to improve speed and connectivity at the Kenyan end of transfers, where funds are deposited into bank accounts or mobile wallets. Greater interoperability could reduce fragmentation and shorten transfer times. Yet the ultimate price paid by senders remains shaped by global market forces beyond Kenya’s control.
The broader context is that remittances are not just financial flows; they are social lifelines. Families depend on them for school fees, healthcare, housing, and daily expenses. Diaspora transfers also underpin Kenya’s balance of payments, helping to stabilize the shilling and finance imports. Any disruption in these flows reverberates across households and the economy. That is why the consultation process is more than a technical exercise. It must test whether higher capital requirements promote resilient competition, whether the instant payment switch integrates smoothly with existing providers, whether interoperability leads to faster transfers, and whether consumer protections keep pace with faster payments. The answers will determine whether Kenya’s next‑generation payment infrastructure can carry USD5 billion a year in diaspora transfers more efficiently and sustainably.
The stakes are high. Remittances have long been Kenya’s most reliable source of foreign exchange, often surpassing earnings from exports and tourism. They cushion households during economic downturns and provide a steady inflow of hard currency. Yet the decline in inflows from the US and Middle East highlights the vulnerability of relying on external jurisdictions. Taxes and regulatory changes abroad can erode Kenya’s inflows overnight. Domestic reforms can improve the rails, but they cannot dictate the costs imposed elsewhere. That tension defines the current debate: infrastructure versus outcome, speed versus affordability, resilience versus competition.
Precious summed it up: “Clear fee information, which the Bill proposes, may help customers see what they pay. The distinction is between infrastructure and outcome. Better rails can reduce friction and make the system more connected.” Transparency may empower consumers, but without competitive pricing, the burden of high costs remains. For policymakers, the challenge is to build a system that is both robust and fair, one that protects consumers while sustaining the flow of foreign currency vital to Kenya’s economy.
As the consultation period closes on 9 October, stakeholders across the financial sector, diaspora communities, and consumer groups will be watching closely. The reforms could reshape how money moves into Kenya, but their success will be measured not only by speed and connectivity but also by affordability and trust. For millions of families, the question is simple: will more of the money sent from abroad actually reach them? For the economy, the answer will determine whether remittances continue to anchor Kenya’s foreign exchange reserves in an era of global uncertainty.
Similar Posts by The Mt Kenya Times:
- Ronaldo walks out of Portugal camp on eve of Denmark clash
- From mobile money to AI: How technology is reshaping small businesses across Mount Kenya
- Stanbic Bank brings Ne-Yo to Nairobi in creative economy push
- Campus traders: Chasing financial freedom, risking it all
- Ruto’s Taita Taveta visit puts land and power at the heart of coastal development
About the Author