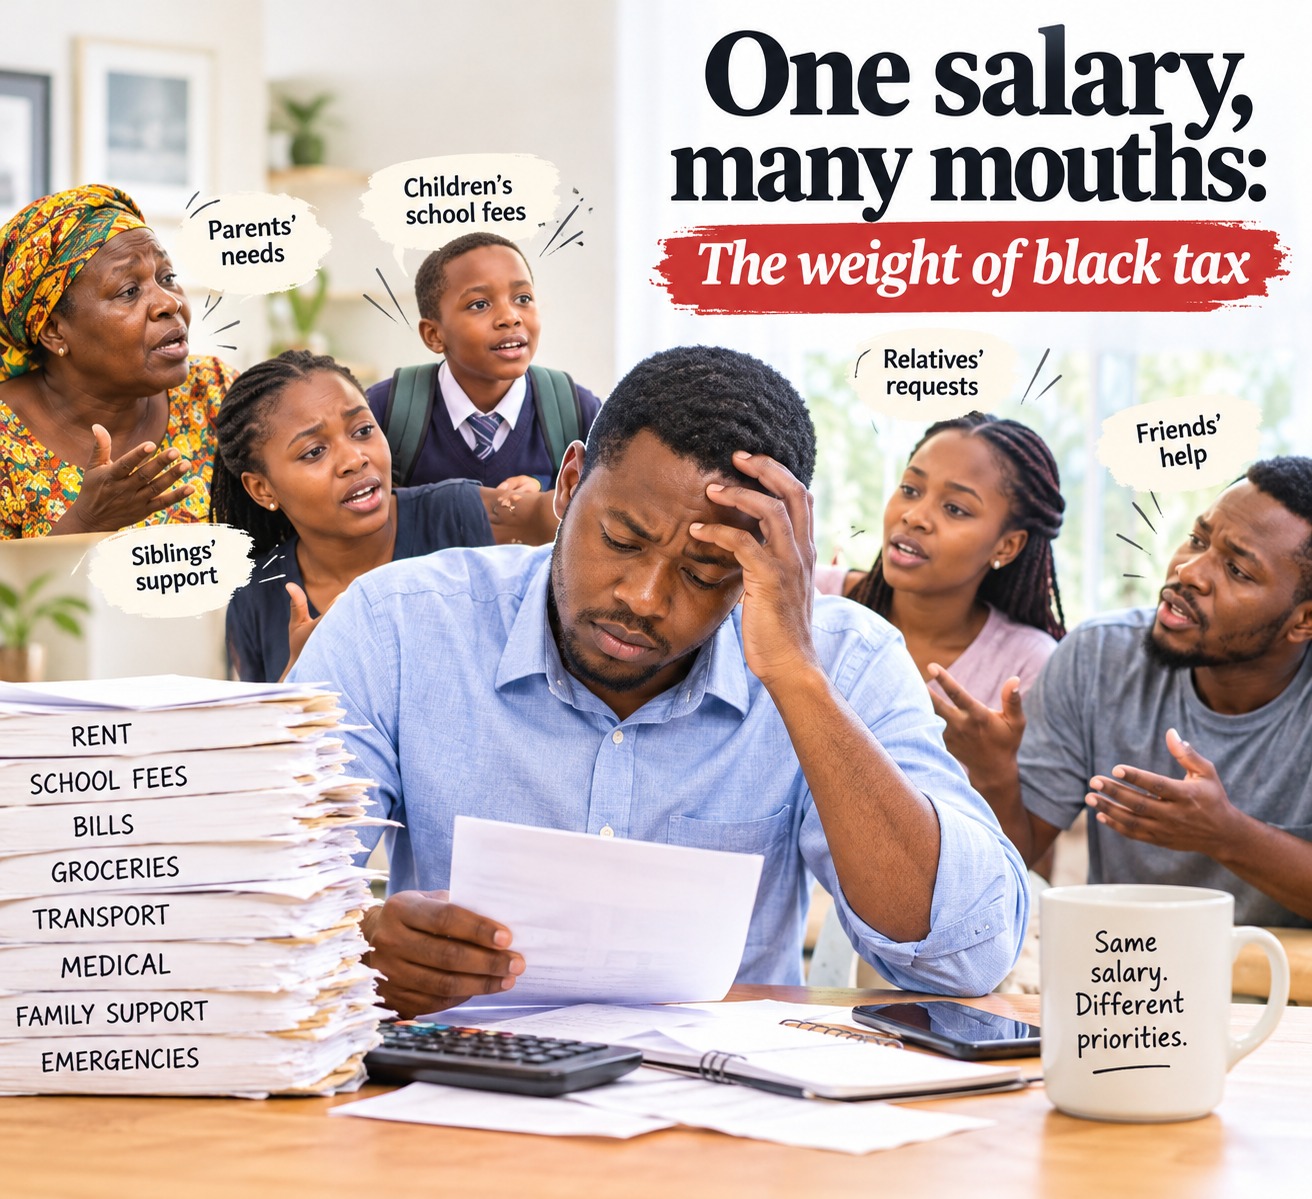
For many Kenyan households, one income supports several people. From parents’ medical bills to siblings’ school fees, helping relatives can ease their financial strain while making it harder to build a secure future.
By Oduor Rosequillet Nabwire
For Kevin Otieno, payday is less a celebration than a reminder of the many obligations tied to his income. The 31-year-old corporate communications officer in Nairobi earns a gross monthly salary of KSh120,000 but takes home about KSh84,500 after statutory deductions.
“Payday in Nairobi isn’t a windfall; it’s an execution of a transfer strategy,” he says. “I don’t hold money; I route it.”
His income must sustain him in Nairobi while supporting his parents in Siaya and his younger sister at Kenyatta University.
Kevin spends KSh22,000 on rent, KSh14,000 on groceries, KSh8,500 on transport and KSh6,000 on utilities, bringing his basic living expenses to KSh50,500.
He also sends KSh20,000 home monthly, allocating KSh12,000 to his parents and KSh8,000 to his sister.
“In Kenya, if you are employed in the city, your salary isn’t just yours. It belongs to your village ecosystem,” he says.
His father takes regular medication for hypertension, while his younger sister depends on the allowance for meals and other expenses.
“Without that support, my parents would struggle with their upkeep and medical expenses, while my sister might turn to mobile debt apps like Fuliza. It’s called ‘Black Tax’, but I see it as duty.”
That sense of duty comes at a cost to Kevin’s own financial security. He saves KSh10,000 through a savings and credit cooperative organisation, leaving him about KSh4,000 for personal spending. An unexpected family emergency or funeral contribution could quickly upset that balance, leaving little room to pursue his long-term goals.
For Wanjiku Njoroge, known to her customers as Shiku, the challenge is managing family commitments on an unpredictable income. The 29-year-old mitumba trader at Gikomba Market also sells clothes online, but her earnings fluctuate with sales rather than arriving as a predictable monthly salary.
Her average monthly net profit, after deducting the KSh38,000 cost of a bale, is KSh52,000. It falls to KSh25,000 during slow periods and rises to KSh85,000 in peak seasons. Yet her family commitments remain unchanged.
“Payday happens fifty times a month, or sometimes not at all for three days straight,” she says. “Some weeks I am holding cash, but that cash isn’t profit. It’s inventory money.”
She spends KSh27,500 on her household and sends KSh16,500 monthly to her mother in Murang’a and younger brother in boarding school. Of that amount, KSh4,500 covers her mother’s diabetic medication, KSh5,000 contributes to household costs, and KSh7,000 goes towards her brother’s school fees.
“My mother needs her diabetic drugs every single month on the 5th,” she says. “School fees don’t have a ‘bad season’ discount.”
She also contributes KSh6,000 monthly to a chama and sets aside KSh2,000 for emergencies and personal needs. The chama offers savings and access to loans for emergencies or restocking, providing an alternative to digital lending apps.
Unlike Kevin, whose salary arrives predictably, Shiku must protect the capital she needs to keep her business running while meeting her family’s needs. When sales fall, balancing those demands becomes harder.
For Everline Taabu, a 34-year-old senior customer service representative at a logistics firm in Nairobi, the consequences of competing financial demands were more severe.
She takes home about KSh68,000 a month, but at the height of her financial difficulties, her monthly obligations reached KSh89,000. Household expenses accounted for KSh38,000, family contributions KSh31,000 and debt repayments KSh20,000, leaving her with a monthly shortfall of KSh21,000.
“People see you working in an office with a decent monthly salary and assume you are thriving,” she says. “But for three years, I was living on a knife edge. Every month, I was running a deficit.”
Her commitments grew as she helped cover her mother’s upkeep, her cousins’ school fee arrears and her uncle’s medical expenses, alongside her own rent and living costs. Rather than turn down requests for help, she borrowed through mobile loan applications and SACCO emergency loans to bridge the gap.
Her KSh120,000 in emergency savings was depleted within six months. As borrowing continued, she began using new loans to manage existing obligations. After sending money home for an urgent medical need, she fell two months behind on rent and received a distress notice from her landlord.
“I was working 50 hours a week, yet I was completely broke and drowning,” she says.
The emotional cost was as difficult as the financial one. She felt that turning down her relatives’ requests for help meant failing them, even when meeting those requests threatened her own financial stability.
“The hardest part wasn’t the money; it was the guilt,” she says. “In African culture, saying ‘I don’t have it’ to your family feels like saying ‘I don’t love you.’”
Her turning point came when she sat down with her family and showed them her pay slip and bank statements. She explained that continuing at the same rate could cost her both her job and her home. She restructured her SACCO loans to consolidate more expensive digital debt and capped her monthly family contribution at KSh12,000, transferring the money into a separate mobile wallet on payday.
“Learning to say ‘No, I cannot afford this right now’ was the hardest emotional hurdle of my adult life, but it was the only thing that saved me from total financial collapse,” she says.
Everline’s experience highlights the challenge of balancing family responsibility with personal financial security. Eric Muchoki, a personal finance expert and director at Customized Solutions Insurance Agency, advises people to set limits on family support based on what they can afford.
“Your support to your parents and siblings should be commensurate with what you can afford. Don’t overcommit what you cannot afford to offer,” he says.
Putting that advice into practice can be difficult when requests involve essential needs such as medication, school fees and unexpected medical bills. The pressure is particularly acute for those regarded as their families’ most dependable source of support. As Everline’s experience shows, repeatedly meeting these demands without clear limits can leave earners struggling to cover their own expenses, even when they have a regular income.
Building financial security also means having savings to fall back on when emergencies arise. Fred Waswa, founder and Group Chief Executive Officer of Octagon Africa Financial Services, stresses the importance of preparing for unexpected expenses.
“True financial security is having the savings to navigate life’s emergencies without falling behind or resorting to debt,” he says.
For Kevin, supporting family means balancing immediate obligations with his own future. For Shiku, it means meeting those obligations without putting her business at risk. For Everline, it meant learning that helping relatives could not come at the expense of her own financial security.
Their experiences show that Black Tax is about more than money sent home. It also involves the expectations placed on the family member who earns and the guilt that can accompany saying no. When those expectations exceed what one person can afford, the consequences can include depleted savings, mounting debt and delayed personal goals.
Supporting family can be an act of love and shared progress. But when one income becomes the safety net for several households, support must remain sustainable. The challenge is not to abandon family, but to help without leaving the person providing that help financially exposed.
Similar Posts by The Mt Kenya Times:
- Mt Kenya Times ePAPER October 12, 2026
- Gachagua’s party storms Kikuyu from afar as 2027 countdown begins
- Counties caught: The KSh100B payroll scandal Kenya can no longer hide
- CS Ogamba: tree planting could generate carbon credit millions to fund education
- Farouk Kibet calls for unity and development as leaders rally behind Ruto’s 2027 re-election bid
About the Author