How Kenya’s economic titans feast while competition law serves as courteous footnote
 The Mt Kenya Times
By Jerameel Kevins Owuor Odhiambo
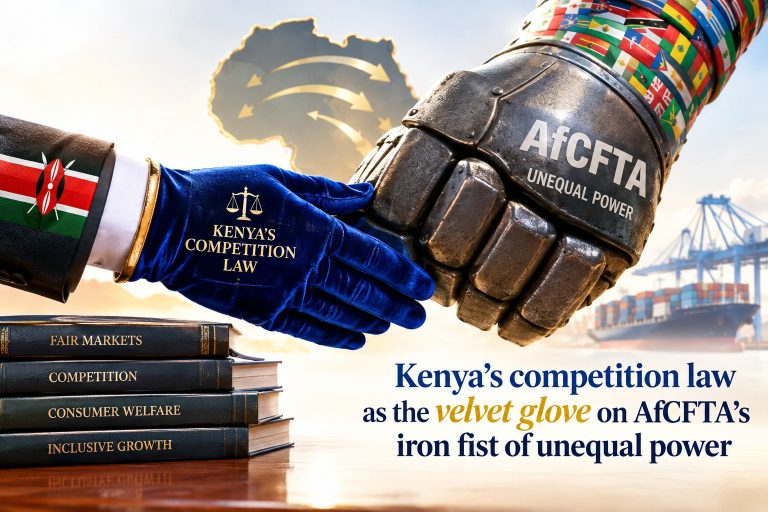
Under Section 50 of Kenya’s Competition Act No. 12 of 2010, the Competition Authority of Kenya is expressly charged to keep the structure of production and distribution under continuous review so as to detect concentrations of economic power whose detrimental impact on the economy outweighs any efficiency gains of integration. The statute itself defines “unwarranted concentration of economic power” to include, among other things, cross-directorships between undertakings producing substantially similar goods or services whose combined market share exceeds forty per cent. That is the cold letter of the law. The living reality is colder still: across cement, steel, animal feed, mobile money, and large-scale banking, a handful of actors sit astride markets like feudal lords, extracting rents while the statute that was meant to restrain them functions more as polite literature than as binding instrument of economic justice.
This is not abstract theory. It is the daily arithmetic of the Kenyan household. When steel manufacturers coordinated prices and restricted imports, the Competition Authority eventually imposed fines totalling KES 338.8 million in 2023. Studies by the World Bank and OECD have long established that such cartels typically inflate prices by twenty to twenty-five per cent. In a country where steel constitutes more than twenty per cent of the cost of housing and public infrastructure, that invisible tax is paid by every family struggling to complete a two-room house and by every county government stretching a limited roads budget. The same pattern repeats in animal feed: four suppliers control more than half the commercial market, with documented practices of input price control, market allocation, and differential pricing that squeeze unintegrated smaller producers. The Authority’s own market inquiry confirmed the oligopolistic structure. Yet the structural grip remains largely intact.
History supplies the bitter continuity. Colonial Kenya organised its economy around licensed monopolies and settler-controlled processing chains. Independence promised a different covenant, yet the new state often simply replaced foreign cartels with state-owned enterprises and politically favoured private conglomerates. The cement sector offers a textbook illustration of the persistence of concentrated power. Investigations more than a decade ago revealed that Lafarge-linked interests held substantial stakes and board representation across major producers, including East African Portland Cement, creating a web of influence that the Authority itself described as exhibiting features of unwarranted concentration. Cross-directorships and shared strategic committees turned putative competitors into co-pilots of the same aircraft. The market share figures were not subtle: one group alone commanded roughly fifty-five per cent. Efficiency arguments were advanced, of course; they always are. But the public interest test under the Act asks whether the concentration unreasonably raises costs or prices or profits. On that measure the defence has frequently rung hollow.
Telecommunications presents an even starker portrait of structural dominance. Safaricom’s share of mobile subscriptions hovers around sixty-five per cent and its grip on mobile money approaches ninety-one per cent. The Herfindahl-Hirschman Index for mobile services places Kenya among the most concentrated markets in sub-Saharan Africa. Higher data prices and lower usage relative to regional peers are the predictable consequences. Banking tells a parallel story: the largest institutions still command nearly seventy per cent of the market and the overwhelming majority of profits. When a few institutions control liquidity, deposits, and lending, the transmission of monetary policy itself becomes filtered through private oligopoly rather than through competitive forces.
The Competition Authority is not idle. In the 2024/25 financial year it investigated seventy-five behavioural antitrust matters: twenty-eight coordinated cartel cases, thirty-nine alleged abuses of dominance, and eight involving trade associations. Manufacturing, agriculture, and ICT featured prominently. Settlements and fines have been extracted. Consumer complaints rose sharply. Yet the deeper structural tools remain under-used. The power under Section 52 to order the disposal of interests sufficient to remove an unwarranted concentration has been exercised with extreme rarity. Abuse-of-dominance infringement decisions have been sparse; OECD peer review data show periods in which multiple investigations closed without findings of infringement. The Authority’s budget and staffing remain modest relative to the scale of the economy and the sophistication of the entities it confronts. Concurrent jurisdiction with sector regulators often produces delay rather than decisive coordination. Criminal sanctions exist on paper fines and potential imprisonment yet prosecutions remain exceptional.
This is not mere administrative shortfall. It is a failure of political will and institutional courage. Concentrated economic power does not remain economically neutral. It translates into political influence, regulatory capture, and the quiet rewriting of the rules of the game. When a handful of firms can shape pricing, block entry, and extract preferential terms from suppliers especially the MSMEs that constitute ninety-eight per cent of Kenyan businesses, generate roughly forty per cent of GDP, and employ seventy per cent of the workforce the social contract frays. The small trader delayed in payment, the farmer paying inflated feed prices, the young entrepreneur unable to access affordable data or competitive credit: these are not peripheral casualties. They are the living evidence that the market has been privatized for the few.
Literary irony abounds. The Competition Act speaks in the language of public interest and consumer welfare; the market answers in the dialect of coordinated silence and shared boardrooms. The statute prohibits conduct that unreasonably increases prices or profits; the cartels treat the prohibition as a risk to be managed rather than a boundary to be respected. One is reminded of the colonial-era marketing boards that claimed to stabilize markets while locking producers into dependent relationships. The form has changed; the substance of concentrated control endures.
Original insight demands we recognise the correlation that policymakers prefer to ignore: high market concentration and weak structural remedies produce not only higher prices but also lower dynamism, reduced innovation, and the crowding-out of domestic capital. Foreign direct investment is welcomed, yet when it arrives already concentrated or quickly achieves dominance through acquisition and cross-holding, it risks reproducing the very dependency the independence generation sought to escape. Sustainability requires both local and foreign capital operating under the discipline of genuine rivalry, not the comfort of shared market power.
The actors who must move are clear and categorical. Parliament must strengthen the structural remedies in the Act, clarify the threshold tests for unwarranted concentration beyond the narrow cross-directorship definition, and resource the Authority adequately so that market studies lead to enforceable orders rather than reports that gather dust. The Competition Authority itself must treat Section 50 and Section 52 as living instruments rather than archival curiosities; disposal of interests and divestiture should cease to be theoretical. Sector regulators in telecommunications, energy, and finance must stop treating competition concerns as secondary to their narrow mandates and begin genuine concurrent enforcement.
The Judiciary, through the Competition Tribunal and the superior courts, must develop a jurisprudence that treats concentration itself when it demonstrably harms the public interest as an independent ground for intervention, not merely a backdrop to behavioural abuse. The Executive must confront the 209 state-owned enterprises, many operating in competitive sectors, and either subject them to the same competitive disciplines or justify their continued public ownership with transparent public-interest tests. Civil society and consumer organisations must refuse the comfortable silence that allows oligopoly to present itself as inevitable modernity. And the business community especially the large players must recognise that short-term extraction through coordination ultimately erodes the legitimacy of the market system on which their long-term prosperity depends.
Kenya stands at a familiar crossroads. One path continues the quiet coronation of concentrated power, dressing it in the language of efficiency and scale while the majority pay the invisible tax. The other path insists that the Competition Act mean what it says: that no concentration, however efficient in the boardroom’s private calculation, may be allowed to outweigh its cost to the public. The words of the statute are already written. What remains is the harder labour of making them sovereign over the empires they were designed to restrain.
The writer is a social commentator
Similar Posts by The Mt Kenya Times:
- Beyond the scars: The grief, fear and hope of living after breast cancer
- Obaga Momanyi hosts free medical camp for Persons with Disabilities in Bonchari
- PP2 graduation: When school ceremonies become a burden on parents
- 89 junior golfers chase glory at NCBA Lisle Shaw Championship
- Scaloni set to stay: Argentina coach to sign 2030 World Cup deal
About the Author