Let’s not throw out the baby with the bathwater: Why responsible digital lending still matters
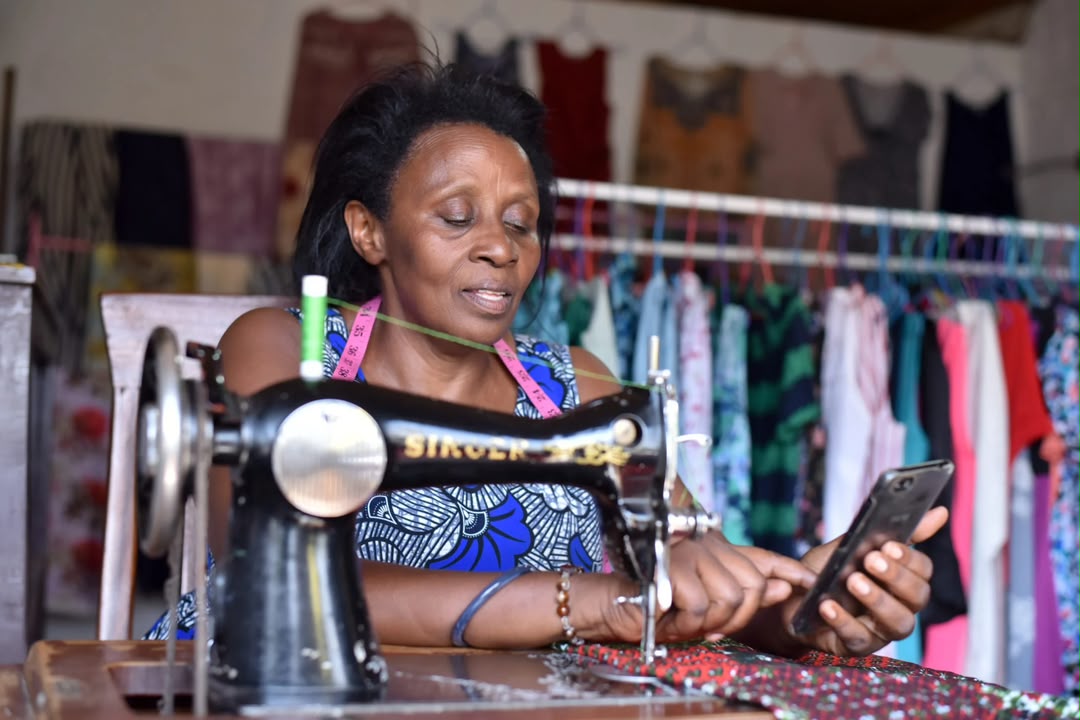
For some Ugandans, mobile loan applications have provided a convenient source of emergency funds, working capital and financial support when traditional financing was out of reach.
By: Daniel Tusiimukye K’abaasa
Few developments in financial services have generated as much public debate in recent years as digital lending. For some Ugandans, mobile loan applications have provided a convenient source of emergency funds, working capital and financial support when traditional financing was out of reach. For others, the experience has involved excessive charges, aggressive debt collection, threats and concerns over the misuse of personal information.
These contrasting experiences have shaped public perceptions of an industry that continues to play an important role in Uganda’s financial ecosystem.
For a small business owner who needs to restock a shop, a farmer preparing for a planting season or a trader facing an unexpected expense, timely credit can make a meaningful difference. Yet traditional financial institutions often require formal financial records, conventional collateral or proof of stable income, conditions that many informal businesses and low-income earners struggle to meet.
While concerns surrounding digital lending must be addressed, they should not overshadow the role responsible providers can play in expanding access to finance. The answer to misconduct is not to dismiss an entire industry, but to hold offenders accountable while supporting practices that serve borrowers fairly.
Bad eggs among the good
The concerns surrounding digital lending are serious. Reports of hidden charges, unclear loan terms, excessive interest, harassment during debt recovery and the misuse of personal data have undermined public confidence in some lending platforms.
In Uganda, the Microfinance Regulation Department under the Ministry of Finance, Planning and Economic Development introduced Digital Lending Guidelines in 2024 in response to concerns about predatory app-based lending and unethical practices. The guidelines address licensing, governance, credit assessment, customer information, loan recovery and consumer protection.
The introduction of these measures reflects an important distinction: the problem is not simply the existence of digital credit, but how it is provided and whether lenders operate within the law. A lender that clearly explains the total cost of borrowing, assesses a customer’s ability to repay, protects personal information and follows fair debt collection procedures operates differently from one that conceals charges or intimidates borrowers.
Treating both as though they represent the same standard of practice risks overlooking the institutions making efforts to build trust and operate responsibly. At the same time, the benefits of digital lending should never be used to excuse abuse. Customers deserve transparent pricing, fair treatment and effective channels for resolving complaints. Lenders that engage in unlawful or harmful practices must be held accountable.
The goal should be a market where responsible providers can thrive and irresponsible actors cannot hide behind the industry’s broader contribution to financial inclusion.
The other side of digital lending
Digital lending uses mobile technology, digital transactions and other relevant data to assess borrowers and deliver credit through accessible platforms. These services can reach customers who might otherwise struggle to obtain financing while reducing some of the administrative requirements associated with conventional lending.
According to a 2026 analysis by the United Nations Capital Development Fund (UNCDF), only about 9–10 per cent of Uganda’s micro, small and medium enterprises (MSMEs) have a formal loan or line of credit. The estimated MSME financing gap stands at UGX31.4 trillion, highlighting the need for alternative approaches to financing businesses and underserved communities.
A responsibly structured digital loan can help a trader purchase stock, a farmer acquire agricultural inputs or a small enterprise manage a temporary cash-flow shortage. For businesses operating on tight margins, timely financing can make the difference between fulfilling an order and losing an opportunity. Individuals can also use suitable credit to manage unexpected expenses when savings are insufficient.
The value of digital lending, therefore, goes beyond the convenience of borrowing through a phone. It lies in whether access to credit helps people manage financial needs, sustain livelihoods and pursue productive opportunities.
Reaching those traditional finance often leaves behind
Financial inclusion involves more than owning a bank account or using mobile money. It also means accessing appropriate financial products on terms that customers can understand and manage.
Women entrepreneurs, young people, rural traders and smallholder farmers may operate viable businesses without the formal records or assets required by conventional lenders. Digital platforms can help bridge this gap by using transaction histories and other relevant information to assess creditworthiness, subject to appropriate consent and data protection safeguards.
Remote applications, quicker decisions and reduced travel costs can also make borrowing more accessible, particularly for people living far from financial institutions. However, easier access must not encourage borrowing without considering repayment capacity. Financial inclusion is meaningful when customers can use financial services to improve their circumstances without becoming trapped in unsustainable debt.
Addressing the bad practices
The concerns surrounding digital lending are serious and should not be minimised. Hidden charges, unclear loan terms, excessive interest, harassment during debt recovery and misuse of personal data can worsen borrowers’ financial difficulties and undermine confidence in formal financial services.
Uganda’s digital lending regulatory framework, including the Digital Lending Guidelines introduced in 2024, seeks to address concerns around digital credit provision and consumer protection.
Not all digital lenders operate in the same way. A provider that communicates borrowing costs transparently, assesses a customer’s ability to repay, protects personal information and follows fair debt collection procedures operates differently from one that conceals charges or intimidates borrowers.
Recognising these differences does not excuse misconduct. Borrowers deserve transparent pricing, fair treatment and effective channels for resolving complaints. Lenders that engage in unlawful or harmful practices must be held accountable.
The objective should be to create a market in which responsible providers can thrive while those that exploit borrowers face appropriate consequences. Consumer protection and financial innovation are not competing priorities; both are necessary for a sustainable digital credit ecosystem.
Building responsibility through collaboration
A sustainable digital lending market requires engagement among lenders, regulators, policymakers, consumer protection organisations and the public.
Digital lenders must review their practices, listen to customer concerns and improve their products. Regulators must provide clear rules, supervise compliance and act against misconduct. Industry associations can encourage shared standards and accountability, while financial education can help borrowers understand interest rates, fees, repayment schedules and the consequences of default.
An important industry initiative in this regard is the Industry Code of Conduct for Responsible Digital Lending in Uganda, launched in November 2025 by the Financial Technologies Service Providers Association (FITSPA), in partnership with UNCDF.
The Code promotes transparent loan terms, responsible credit assessment, data protection, fair debt collection and effective complaints handling. It complements the existing legal and regulatory framework while establishing expectations for participating lenders.
At the 8th FITSPA Annual Fintech Conference, held at the Sheraton Kampala Hotel on October 6 and 7, 2026, FITSPA and UNCDF recognised eight responsible digital lenders that had subscribed to the Code: Furaha Financial, Zenka Finance, Fido, Unifi, M-KOPA, Flow Global, JUMO and Numida.
The recognition highlighted industry efforts to promote responsible lending and strengthen confidence in digital financial services. However, subscribing to a code of conduct is only a starting point. Its value depends on whether lenders apply its principles in their daily operations, from assessing repayment capacity to protecting customer information and resolving complaints.
Industry commitments must therefore be supported by effective supervision, accountability and continued engagement with borrowers.
Credit must support productive economic activity
As Uganda pursues its Tenfold Growth Strategy, which aims to expand the economy to US$500 billion by 2040, access to appropriate financing remains important for enterprise development, investment and job creation.
Digital lenders can contribute by developing products that support productive activities rather than focusing solely on the number of loans disbursed. Credit that helps a trader expand stock, a farmer invest in production or a small enterprise fulfil a contract can support employment, strengthen supply chains and stimulate economic activity.
This requires lenders to consider whether their products suit the customers they serve. Loan amounts, pricing and repayment schedules should reflect borrowers’ circumstances, and credit assessments should help prevent customers from taking on obligations they cannot reasonably meet.
More lending does not automatically mean greater financial inclusion. The goal should be to expand access to useful financial services while protecting customers from unsustainable debt.
Responsible practices can also strengthen the industry’s long-term sustainability. Transparent terms, fair treatment and effective complaints resolution help build trust and maintain customer relationships.
Preserving the good while confronting the bad
Uganda’s digital lending industry faces a defining challenge: responding to legitimate public concerns without losing sight of the financial needs that make digital credit valuable.
The experiences of borrowers who have suffered harassment, hidden charges or unfair treatment must inform stronger safeguards and enforcement. Equally, the potential of responsible lenders to serve small businesses, reach underserved communities and provide timely financing deserves recognition.
The way forward is not to choose between consumer protection and financial innovation. Uganda needs both.
That means enforcing regulations, strengthening industry standards, improving financial literacy, encouraging responsible product development and ensuring borrowers have effective ways to seek redress. It also means assessing lenders by their conduct, transparency and treatment of customers rather than allowing the actions of a few to define the entire industry.
Digital lending is not without its challenges, and it should never be beyond scrutiny. But neither should its potential be discarded because some providers have failed to uphold the standards expected of them.
Let us hold bad actors accountable, support responsible innovation and preserve the opportunity for digital lending to work for the people and businesses that need it most.
Similar Posts by The Mt Kenya Times:
- Mt Kenya Times ePAPER October 29, 2026
- Ruto courts Moscow as Africa’s big powers rewrite the rules of engagement
- The running-mate puzzle: Who blinks first?
- Jubilee’s coalition gambit: The opposition clock is ticking towards 2027
- From Moscow with ambition: Ruto bets on Russia to rewrite Kenya’s economic story before 2027
About the Author